Schools are teaching kids calculus and sending them into debt they can’t calculate
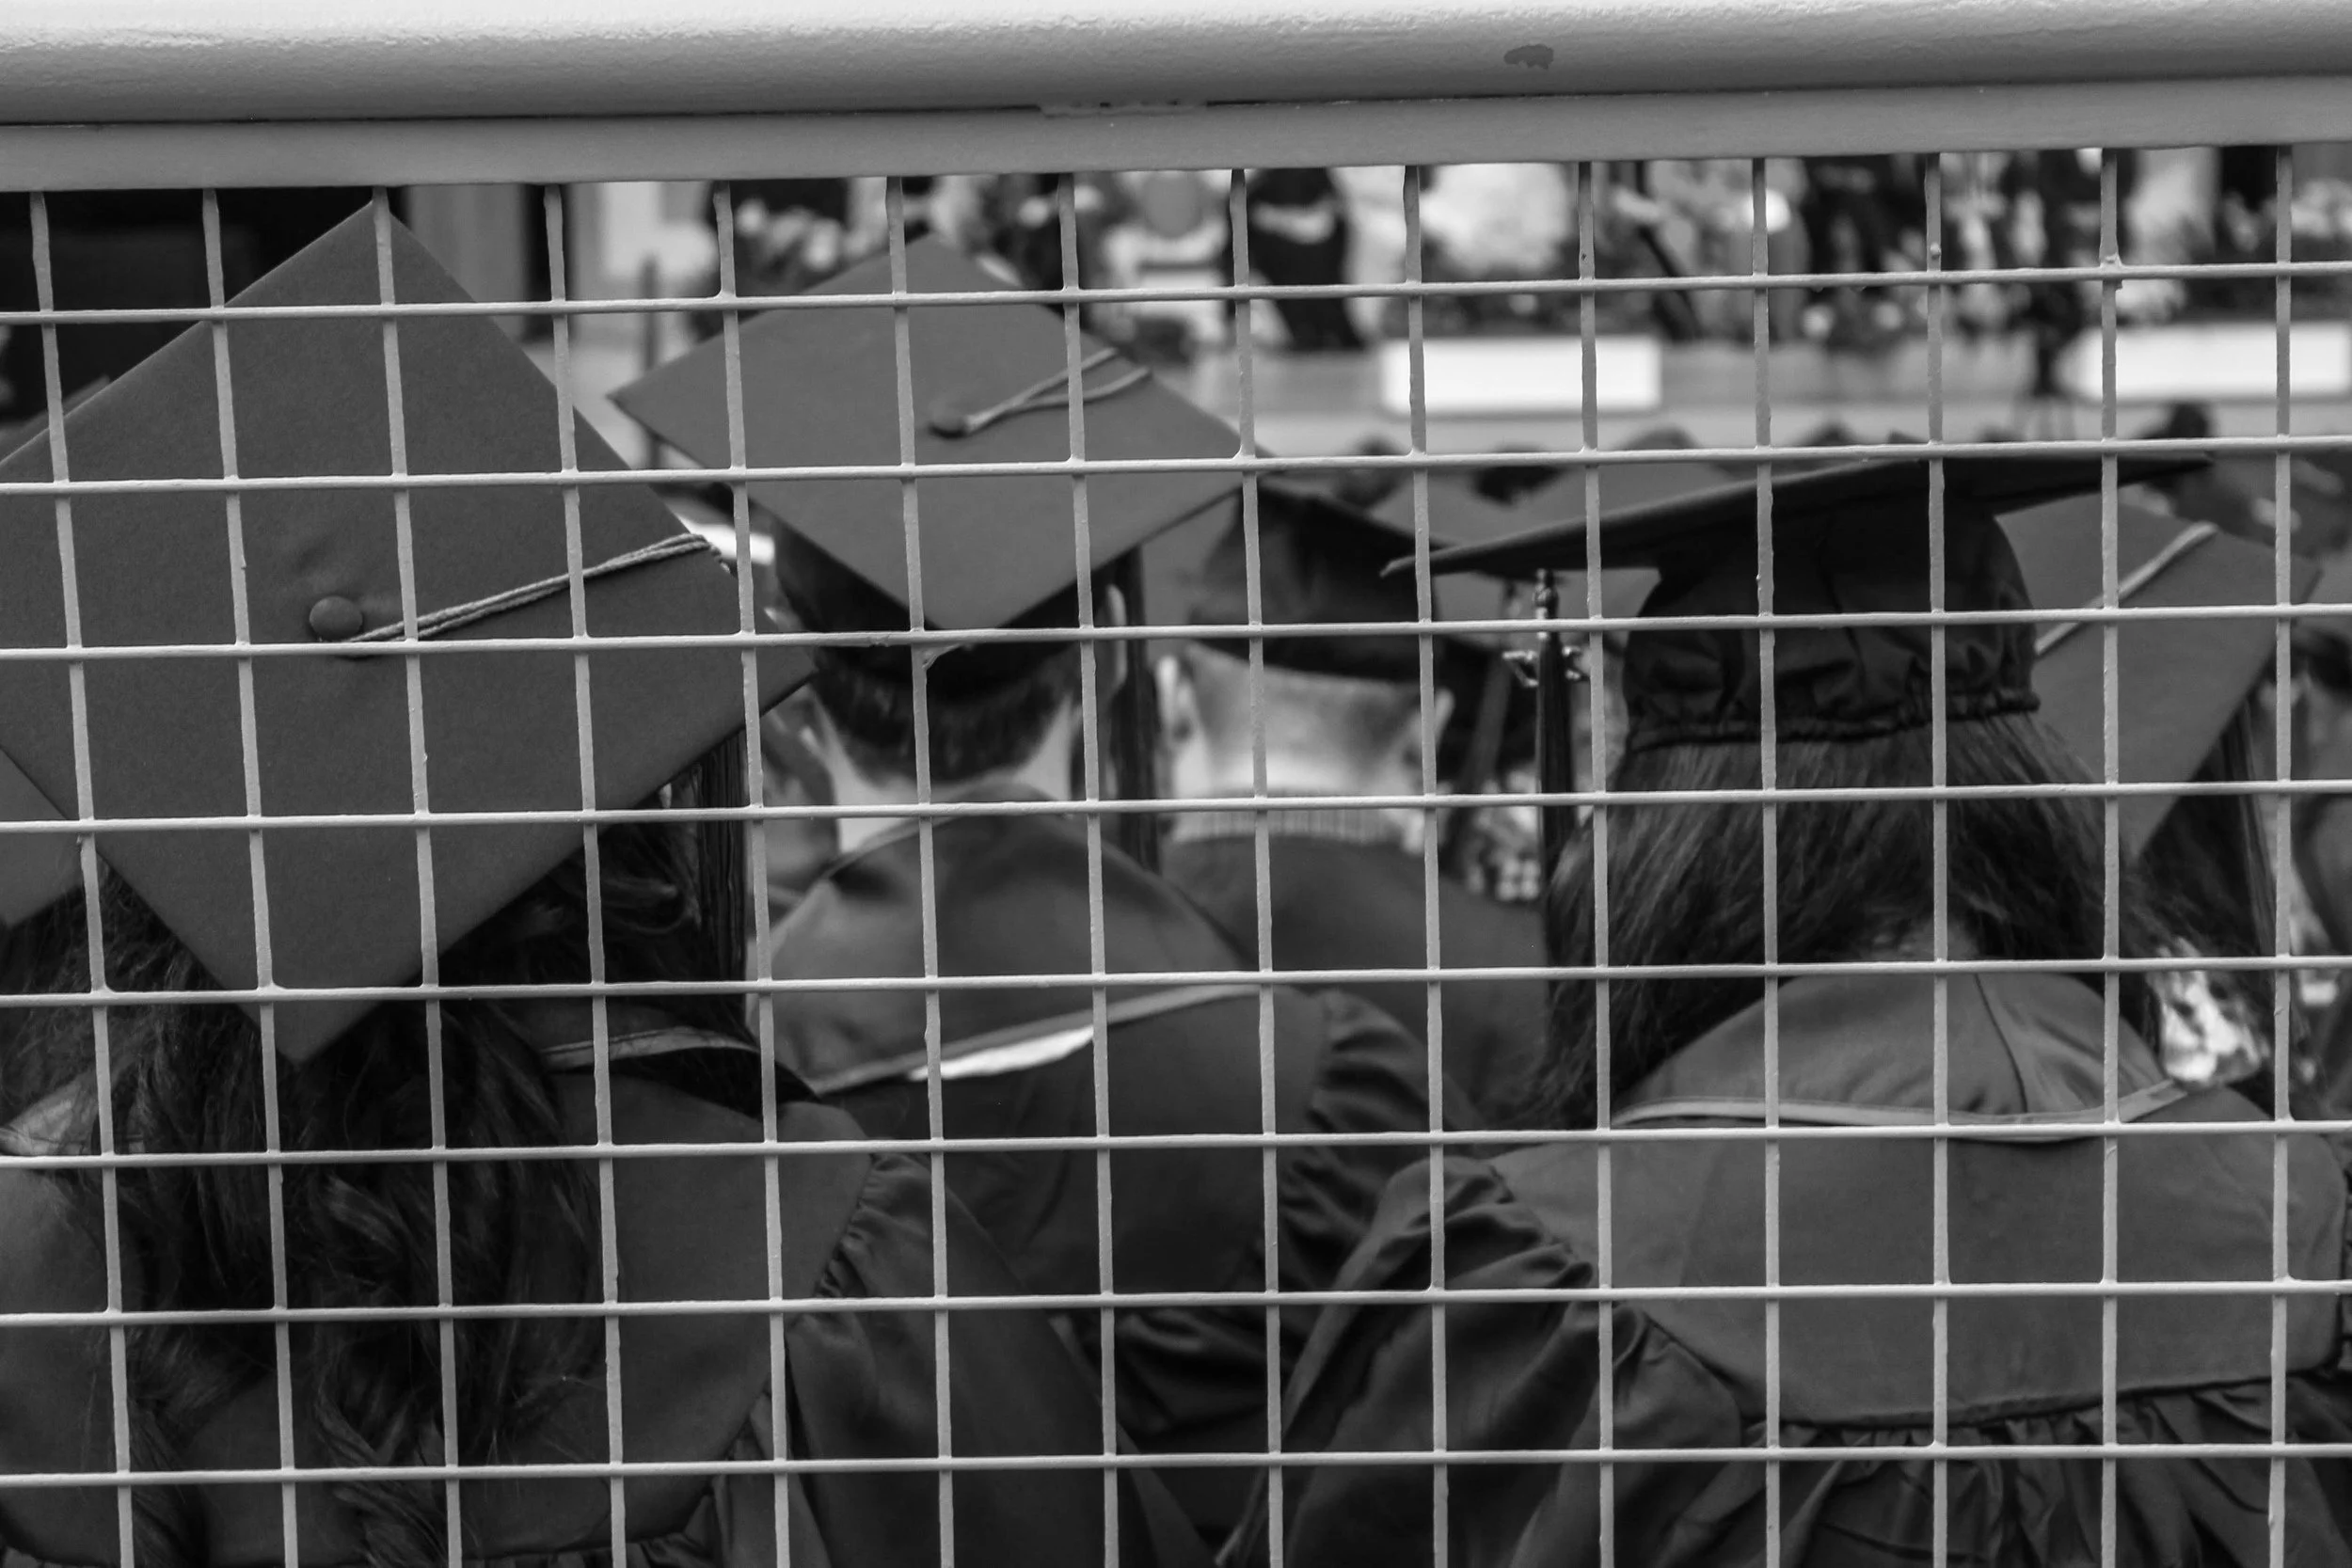
Students at their high school graduation ceremony, June 2026. Photo credit: Ande Richards
NEWARK, NJ — Within weeks of arriving at Seton Hall University, my brother was surrounded by credit card offers. Companies set up tables on campus, filled his inbox and pitched their cards as free money, free rewards and freedom itself.
He signed up.
It didn’t feel like a decision with consequences. It felt like something everyone around him was doing. Only later, when the bill and interest came due, did he understand what he had agreed to.
My brother’s experience shows why New Jersey was right to require high school students to take a personal finance course before graduating. It also shows why Newark should not wait until the state deadline to make sure students receive that education.
The Newark Public Schools Class of 2026 had much to celebrate. Among the students graduating from the district’s 17 high schools, 190 had already earned associate degrees. Another 508 seniors were honored for maintaining GPAs of 3.5 or higher.
By any measure, these are accomplished students. But some will enter adulthood without knowing how to build a budget, file taxes, improve a credit score or understand the interest attached to a loan.
Within months of graduation, they may be opening their first credit cards and signing student loan agreements worth tens of thousands of dollars. These are major financial decisions, yet students are expected to make them without always understanding how debt and interest work.
New Jersey lawmakers have taken an important step to change that.
With the passage of S-3462, sponsored by state Sens. Vin Gopal and Angela McKnight, high school students will be required to complete a course devoted exclusively to personal finance. The course will cover budgeting, savings, credit, debt, banking, taxes, investing and college financial planning.
The graduation requirement will first apply to students entering 12th grade during the 2027-28 school year. That means it will come too late for students like me, who will graduate before then.
New Jersey’s existing graduation requirements can be satisfied with broader courses in financial, business, economic or entrepreneurial literacy. Those classes do not necessarily teach students how to manage their own money. S-3462 closes that gap for future graduating classes. Newark should begin preparing now and, if possible, offer the course before the state requires it.
Credit cards are only the first door. Student loans are the second, and they open even faster.
My brother also had to borrow money for college. Telling students not to take out loans is not a realistic answer for many Newark families. Without loans, higher education may be out of reach.
But borrowing money without fully understanding the repayment terms can shape a person’s life for years. My brother now has to consider that debt when making decisions about his future. His experience was not simply the result of a careless choice. It was a predictable outcome of asking an 18-year-old to enter financial contracts he had never been taught to read.
Some people argue that financial education should be left to parents. But many adults never received that education themselves. Not every parent understands credit, investing or retirement accounts well enough to teach those subjects.
Others may say schools do not have room in an already crowded curriculum. But schools regularly adjust what they teach to prepare students for the world they are entering. In a world of student loans, credit cards, digital banking and retirement accounts, financial literacy is no longer optional.
It is a necessity.
A personal finance course should teach students how to understand credit cards and student loans, complete W-2 and W-4 forms, create a budget, build credit and prepare for major purchases such as a car or home. A successful graduate should know not only how to solve for x, but how to manage the financial responsibilities waiting after graduation.
As I begin my senior year, I will soon be applying to colleges and comparing tuition, financial aid and student loan offers. Watching my brother deal with the consequences of decisions he made as a freshman has made me realize how unprepared I am to make those choices.
I know how to calculate a circle’s circumference, but I have never been taught how interest accumulates, how to compare loan terms or how to use a credit card responsibly. In less than a year, I will receive a diploma and be expected to make financial decisions that could follow me long after graduation.
My brother learned how credit and debt work after the bills arrived. For me and my current classmates, the new requirement arrives too late. Unless Newark acts sooner, we may have to learn the same way.
Passing S-3462 was the right decision. Now Newark Public Schools should make sure its promise reaches students as soon as possible. Newark’s students deserve the opportunity to understand what they are signing before those decisions shape their futures.
The opinions expressed here do not reflect that of Public Square Amplified.
This story has been updated to reflect the passage of NJ S3462.